
Insights
Centralized Versus Federated AI Budgets
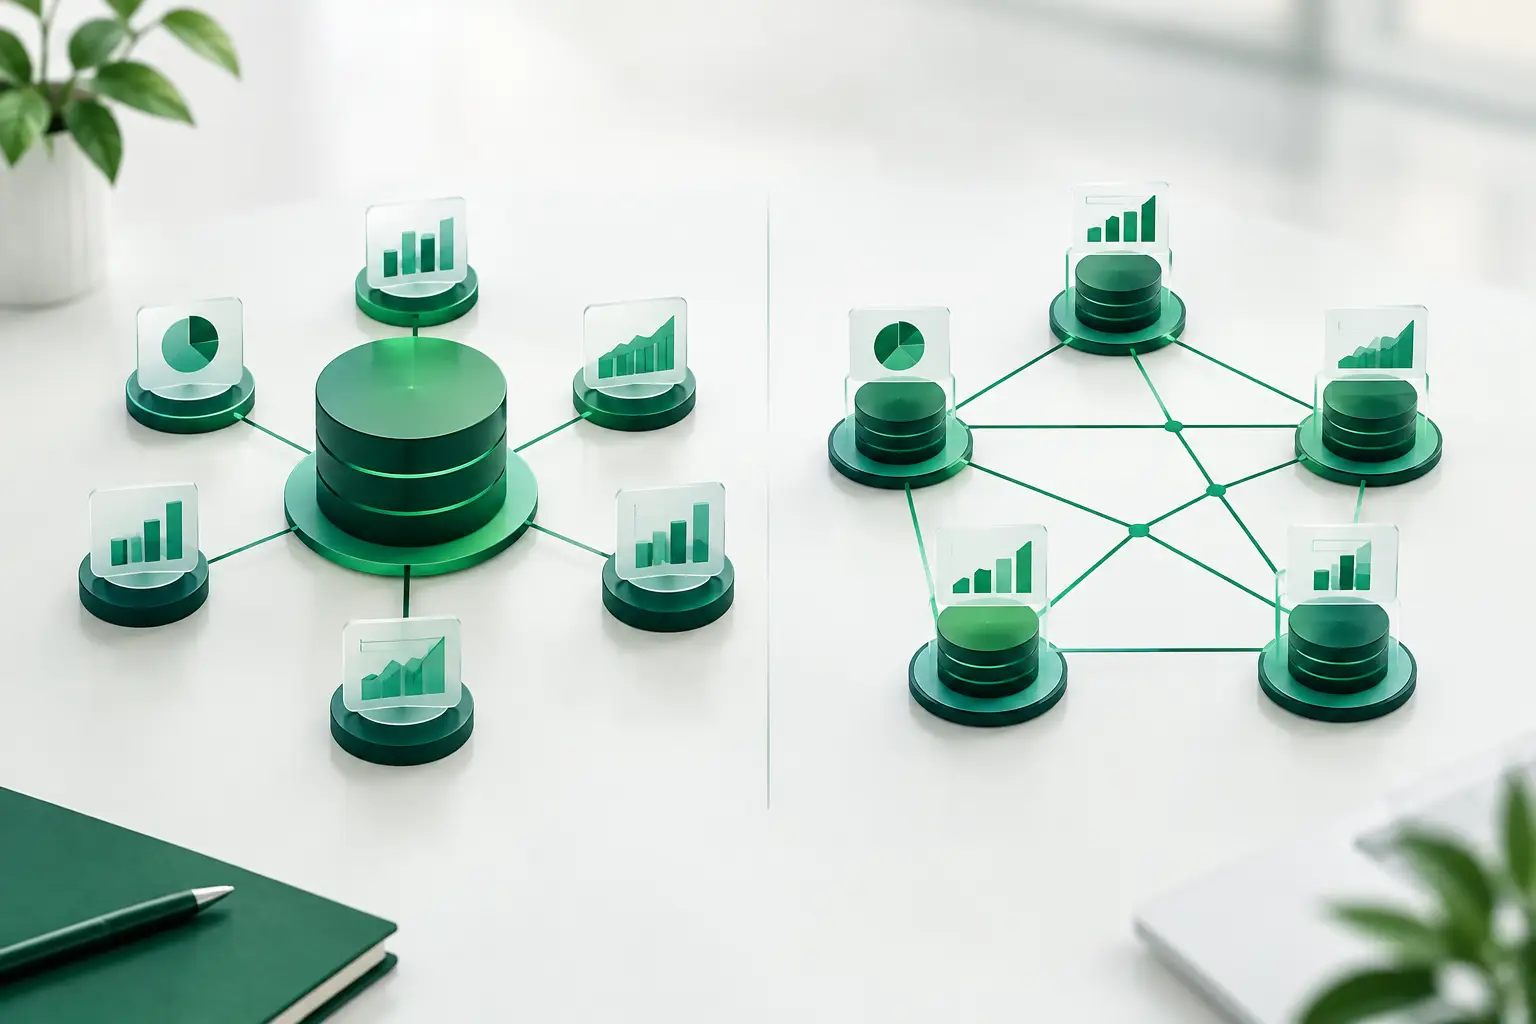
A single $280,000 AI invoice can mean two very different things. It may represent a deliberate enterprise capability, funded and governed as shared infrastructure. Or it may be the combined activity of 18 teams, each assuming someone else owns the overage. The difference is not merely organizational design. It determines whether leaders can forecast AI spend, explain it at month-end, and make sound decisions about expansion.
The choice between centralized versus federated AI budgets is therefore a question of financial accountability. Most organizations will not land at either extreme. The practical answer is usually centralized visibility and controls, paired with federated ownership of the demand that drives cost.
What each budget model actually means
A centralized AI budget sits with a corporate function, often IT, a data and AI team, or an innovation office. That group pays vendor invoices, manages platform commitments, and approves access. Business teams consume AI services without carrying the expense directly, or they receive only informal showback reports.
This model is useful when a company is early in AI adoption. It creates a controlled path to experimentation, avoids forcing every department to negotiate separate vendor arrangements, and lets a central team establish security, procurement, and architecture standards. It also makes sense for genuinely shared costs, such as an AI gateway, common evaluation tooling, or a centrally operated retrieval service.
A federated budget model assigns AI spending authority to business units, cost centers, products, or programs. Customer support pays for its support agent. Legal owns the cost of contract-review workflows. A product organization owns model inference associated with its embedded features. Finance can then compare cost with the business outcome each team is accountable for delivering.
Federation is not the same as handing teams a corporate card and calling it autonomy. A workable federated model requires consistent usage data, a shared allocation policy, and defined controls. Without those, it simply distributes invoices while preserving uncertainty.
Why the centralized-versus-federated AI budgets debate gets stuck
Finance often favors federation because it places costs where decisions occur. Technology leaders often favor centralization because vendor accounts, model access, and infrastructure controls cannot be managed effectively by dozens of independent teams. Both positions are reasonable, but each becomes incomplete when it treats AI spend as a single type of cost.
AI spending usually contains at least three categories. Direct consumption costs are attributable to a team, agent, project, or customer workflow, such as model tokens or hosted inference. Shared platform costs support many teams, such as gateway operations or centrally managed vector infrastructure. Enterprise capability costs cover training, architecture, governance, and early experimentation.
Trying to fund all three categories from one central budget obscures the economics of production use cases. Trying to charge every shared dollar directly to departments creates administrative friction and arguments over pennies. The budget structure should follow the cost behavior.
Consider a company spending $100,000 per month on AI. Of that amount, $72,000 comes from identifiable production workloads across five departments, $18,000 supports shared platform services, and $10,000 funds an enterprise experimentation program. Charging the full $100,000 to IT makes department-level unit economics invisible. Charging every platform engineer's time to individual prompts creates a reporting exercise no one trusts.
A better approach is to assign the $72,000 directly, allocate the $18,000 under a documented driver, and retain the $10,000 in a centrally sponsored innovation budget. The accounting treatment becomes understandable because it reflects operating reality.
Use a hybrid operating model, not a compromise without rules
A hybrid model works only when responsibilities are explicit. The central AI or platform team should own vendor governance, account architecture, access standards, rate-limit policies, consolidated billing, and the measurement system. It should not become the permanent owner of every department's consumption.
Business leaders should own approved use cases, demand forecasts, and the variable cost generated by their teams, agents, and products. They need timely visibility into consumption before the invoice arrives, not a quarterly report that cannot change behavior.
Finance should own the allocation policy, chart-of-accounts mapping, materiality thresholds, and close process. That means deciding which costs are direct, which costs are allocated, when an expense is recharged, and what evidence supports the resulting journal entries. Finance should not be expected to reverse-engineer token consumption from a vendor invoice.
This division is particularly important when an AI workflow crosses organizational boundaries. A sales assistant may be built by the platform team, deployed by sales operations, and used by account executives. The direct inference cost might belong to sales, while the shared gateway cost is allocated across all consuming departments based on measured requests or spend. The build cost may sit in a centrally funded program until the organization decides it is an ongoing product capability.
Match allocation methods to what leaders can influence
The best allocation driver is not always the most technically precise one. It is the one that is measurable, explainable, and sufficiently connected to the behavior a team can control.
For direct model usage, allocate by actual cost whenever possible. If a support agent generated $14,600 of identifiable inference spend in a month, assign that amount to the support cost center. If an internal platform serves multiple teams but does not expose clean downstream usage, allocate its shared costs by a stable driver such as request volume, active agents, processing time, or direct AI spend.
Avoid using headcount as a default allocation driver for AI infrastructure. It is easy to obtain, but it rarely reflects consumption. A 20-person engineering team operating a high-volume agentic workflow may use far more resources than a 200-person department with occasional internal access.
Document the policy in plain language. For example: direct model and cloud AI usage is charged to the consuming cost center based on measured usage; shared gateway and observability costs are allocated monthly based on each cost center's share of direct AI spend; enterprise research costs remain in the corporate AI program budget. This is specific enough to execute and straightforward enough to explain to an auditor or department leader.
At month-end, the process should produce a defensible entry, not just a dashboard. If IT initially pays a $72,000 vendor invoice on a central cost center, the company may debit departmental AI expense accounts for their measured consumption and credit a central IT clearing account. The exact accounts depend on the chart of accounts, but the principle is consistent: usage data must become bookable financial evidence.
Budget for consumption, commitments, and uncertainty separately
AI forecasts fail when organizations treat all spend as a flat monthly run rate. Usage-based costs move with transaction volume, model selection, workflow design, retries, and adoption. A budget needs operating assumptions, not a single number copied from the latest invoice.
For each material use case, forecast a unit cost and a volume driver. A document-processing agent may cost $0.42 per document. A support workflow may cost $0.18 per resolved case. A product feature may cost $0.03 per active user interaction. Multiply the expected unit cost by forecast volume, then review variance in both components. Did demand increase, or did the workflow become more expensive per unit?
Keep vendor minimums, annual commitments, and shared platform charges visible as separate fixed or semi-fixed budget lines. This prevents a common mistake: treating an annual platform commitment as a business unit overage when the organization has not yet grown into the capacity it purchased.
Finally, establish a contingency policy for experimentation and model changes. Early-stage workflows can vary materially as teams adjust prompts, tools, retrieval patterns, and model routing. A defined innovation reserve is more honest than burying this volatility in a department's operating forecast and later calling it a surprise.
Controls should guide decisions before spend becomes a variance
Budgets without operating controls are retrospective reports. Useful controls include team-level spending thresholds, alerts for unusual cost per transaction, approval rules for new production agents, and exception review when a workflow exceeds its forecast by a material amount.
The purpose is not to block usage at the first sign of variance. A support team that spends more because it resolved more customer cases may be producing a favorable outcome. The review should ask whether the unit economics still work: what did the company receive for the additional cost, and who has authority to continue it?
Set thresholds according to materiality. A $200 variance does not need executive escalation. A workflow that doubles its monthly forecast or creates a $25,000 unplanned commitment likely does. Clear thresholds keep finance involved in meaningful decisions without turning every technical adjustment into a budget committee meeting.
Start with attribution before reorganizing budgets
Many companies debate centralized versus federated AI budgets before they can answer a simpler question: who generated last month's spend? Reorganizing budget ownership without reliable attribution only moves an opaque number from one cost center to another.
Start by mapping every AI vendor, cloud AI service, gateway, agent, and internal project to an owner. Measure usage at the lowest practical level, then map it to cost centers and financial periods. Run showback for one or two close cycles before introducing chargebacks. This gives teams time to validate the data and exposes gaps in tags, project identifiers, and ownership.
Once the organization trusts the numbers, budget accountability becomes far less contentious. The goal is not to make every team manage infrastructure. It is to ensure every material AI cost has an owner, a business purpose, and a path into the forecast and general ledger. That is how AI can grow from a large unexplained invoice into a managed business resource.
About Brian Diamond
Brian Diamond is a fractional Chief AI Officer who works with mid-market and enterprise organizations on AI strategy, governance, and operations. In 2001 he founded LanStatus, a managed services provider based in Trumbull, Connecticut, with named partnerships across Microsoft, HPE, Citrix, and VMware. He brings 25 years of infrastructure operations to AI leadership and publishes the CAIO Brief.
Also publishes at: day9.coffee · ChiliStation · PlotLuck · Beacon
Subscribe to the CAIO Brief for practical AI leadership every week.
Request an Onaro demo